What Credit Score Do You Actually Need to Buy a Home in Alberta?
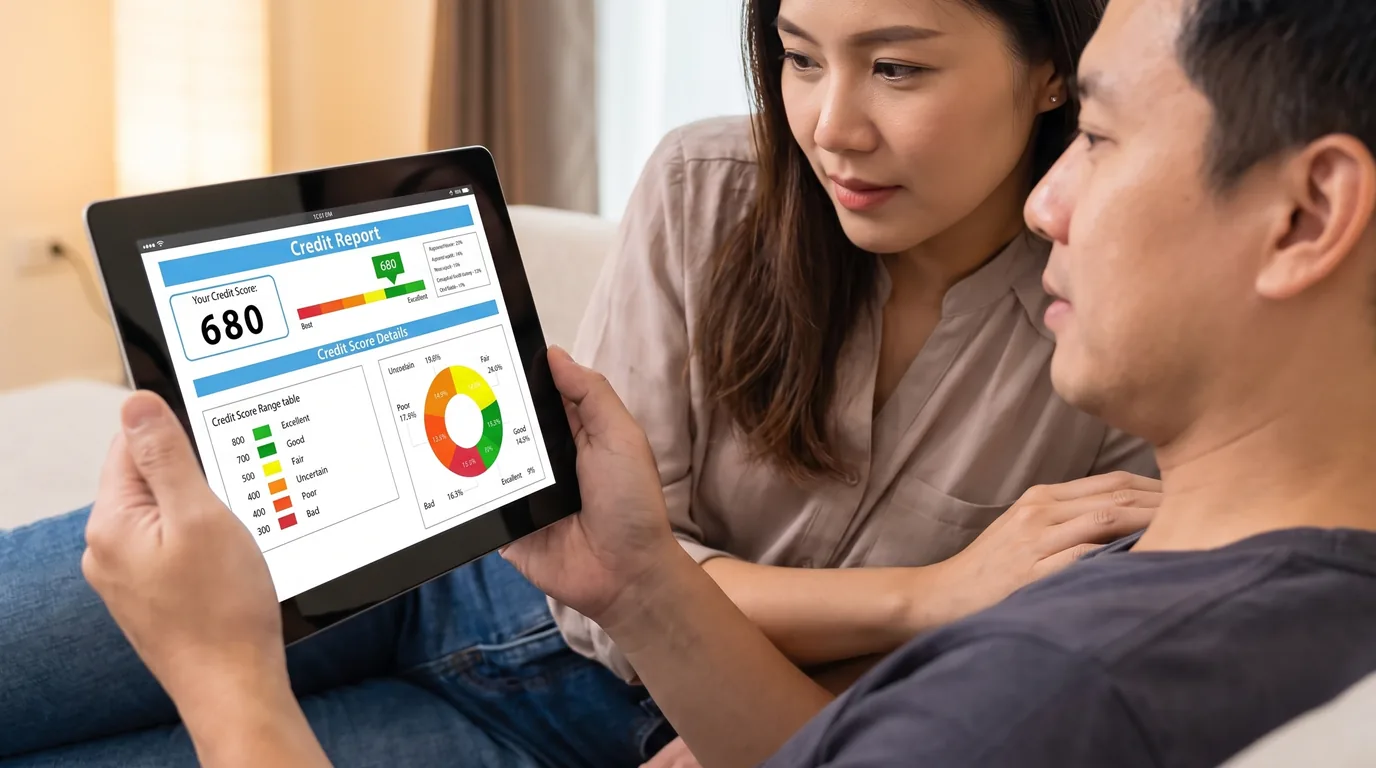
“What credit score do I need to buy a house?” has a specific answer in Canada, which is unusual for a mortgage question. There is a published floor for insured financing. What that floor does not tell you is that clearing it and getting a good mortgage are two different achievements — the score decides whether you qualify, and then keeps working on what you pay.
The short answer
CMHC-insured financing — the route most first-time buyers with less than 20% down use — requires a minimum credit score of 600 from at least one borrower. Individual lenders often set their own thresholds higher. Above the floor, a stronger score does not change whether you qualify so much as what rate you are offered.
Key takeaways
- 600 is the CMHC minimum for insured mortgage financing, from at least one borrower on the application.
- It is a floor, not a target. Many lenders want more, and pricing improves well above it.
- Your score is only one input. Debt service ratios cap housing costs near 39% of income and total debt near 44%.
- Payment history is the largest single factor in a Canadian credit score — larger than balances, and far larger than the number of accounts.
- Multiple mortgage credit checks inside a short shopping window are treated as one inquiry, so comparing lenders does not compound the damage.
Who this guide is for
Edmonton first-time buyers who want to know where they stand before a lender tells them, and anyone who has been told a number by a friend and would like to know what the actual published requirement is.
The floor, and what sits above it
For a mortgage with less than 20% down, the loan must be insured, and CMHC requires a minimum credit score of 600 from at least one borrower. That is the published bar and it is genuinely a bar — below it, insured financing is generally unavailable regardless of income.
Above it, the effect changes character. The question stops being “will they approve me” and becomes “what will they charge me”. Broadly: the low 600s clears the requirement but leaves you with fewer lenders and less negotiating room; the 700s opens most of the market; the 750-plus range is where the best advertised pricing generally lives.
What actually moves a Canadian credit score
- Payment history — the single largest factor. One missed payment reported to the bureau does more damage than almost anything else you can do.
- Credit utilisation — how much of your available credit you are using. Keeping balances well under the limit, ideally under thirty per cent, helps materially.
- Age of accounts — a long-held card in good standing is an asset. Closing your oldest card to “tidy up” before a mortgage application is a common and costly mistake.
- New credit — several applications in a short period looks like distress. Do not finance furniture for the new house before closing.
- Mix — a modest range of credit types helps slightly, but it is far less important than the first two.
What to do in the six months before applying
Pull your own report from both Equifax and TransUnion — you are entitled to it, and checking your own file is a soft inquiry that does not affect your score. Errors are more common than people assume, and a mistaken collection or an account that is not yours takes time to dispute, so find it early rather than during underwriting.
Then: pay everything on time without exception, bring balances down, leave old accounts open, and do not apply for anything new.
Shopping several lenders will not wreck your score. Canadian credit bureaus treat multiple mortgage inquiries inside a short window as a single event, precisely so that comparing offers is not punished.
The score is not the whole application
A strong score with unstable income or heavy existing debt still fails the ratios. A moderate score with steady income, a clean payment record and a decent down payment frequently succeeds. The score decides which lenders will look; the ratios and the stress test at the greater of contract plus 2% or 5.25% decide how much they will lend.

Ryan McCann
Ryan is an Edmonton-based REALTOR® with MaxWell Polaris and the person behind Padster. He's helped over 2,200 clients in the Edmonton area buy and sell their home.
Contact Ryan today at 780-964-8445 to talk through your next step.
Last reviewed 22 August 2026. General information for Edmonton-area buyers — not individualized financial, mortgage, legal or tax advice. Mortgage rules, government programs and market figures change; confirm current details with a licensed mortgage professional, an Alberta real-estate lawyer, or the relevant government source before making a decision. Padster is not a brokerage.
Sources
- CMHC — Calculating GDS / TDS
- Financial Consumer Agency of Canada — Preparing to get a mortgage
- Office of the Superintendent of Financial Institutions — Minimum qualifying rate for uninsured mortgages
- CMHC — Information for consumers
Your next step
Get a real number, not a guess
A broker who works with first-time buyers, renters and newcomers every day. Free, no obligation.
Request a free pre-approval introductionFrequently asked questions
What is the minimum credit score to buy a house in Canada?
CMHC requires a minimum of 600 from at least one borrower for insured mortgage financing, which is the route most buyers with less than twenty per cent down use. Individual lenders may set higher thresholds of their own.
Is a 600 credit score good enough for a mortgage?
It clears the CMHC floor but leaves fewer lender options and less pricing room. Scores in the 700s open most of the market, and the best advertised rates generally sit above 750.
Does checking my own credit score lower it?
No. Checking your own report is a soft inquiry and has no effect on your score. It is worth doing well before you apply so any errors can be disputed in time.
Will shopping multiple lenders hurt my credit?
Not meaningfully. Canadian credit bureaus treat multiple mortgage-related inquiries within a short window as a single event, so comparing offers is not penalised.
Should I close old credit cards before applying for a mortgage?
Generally no. Age of accounts helps your score, so closing your oldest card can lower it. Keeping it open with a zero or low balance is usually better.
What matters more than my credit score?
Your debt service ratios and income stability. CMHC guidelines cap housing costs near 39% of income and total debt near 44%, tested at the stress-test rate — a strong score does not override those.