Renting vs. Buying a Condo in Edmonton: The Fee Math Nobody Runs
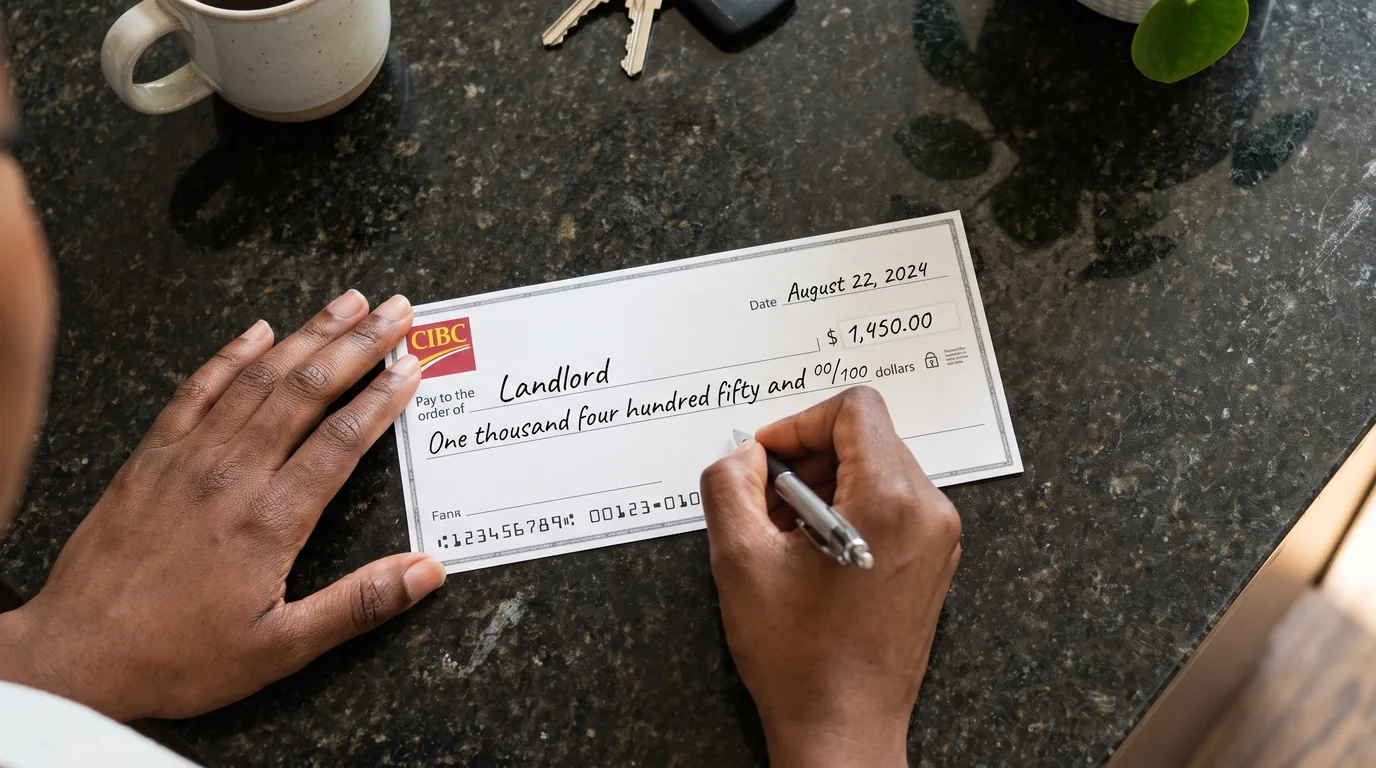
A condo is the most common first purchase in Edmonton, and it is the one where the rent-versus-buy comparison most often goes wrong. The reason is a single line most people leave out of the arithmetic entirely: the condo fee. Left out, a condo looks cheaper than it is. Put in properly, it sometimes still wins — but you will know why.
The short answer
Compare your rent against the mortgage payment plus the condo fee, never the mortgage alone. A condo with a lower list price than a house can cost more per month once its fee is counted, and a fee is not a fixed thing — it rises with the building’s costs and can be supplemented by a special assessment if the reserve fund is thin.
Key takeaways
- The honest comparison is rent vs. mortgage payment + condo fee, not rent vs. mortgage payment.
- Lenders include a portion of the condo fee in your debt service ratios, so a high fee lowers what you can borrow as well as raising what you pay.
- A high fee is not automatically bad and a low fee is not automatically good — what matters is what the fee covers and whether the reserve fund is adequately funded.
- Ask for the reserve fund study and recent board minutes before conditions come off. In Alberta these documents are part of ordinary due diligence.
- A special assessment is the risk a low fee often hides: an underfunded building bills owners directly when the roof or the parkade finally needs work.
Who this guide is for
Edmonton renters comparing their current apartment rent against buying a condo or townhouse, and anyone who has looked at a condo list price, thought it looked affordable, and not yet added the fee.
Why the condo fee changes the comparison
Rent is a single number covering everything. A condo’s monthly cost is at least two numbers: the mortgage payment and the condo fee, plus property tax and your own unit insurance. Compare only the first against your rent and you have understated the real cost by hundreds of dollars a month.
The effect on borrowing is less obvious and just as real. Lenders count a share of the condo fee inside your gross debt service ratio — the one capped near 39% of income under CMHC guidelines. A large fee therefore reduces the mortgage you qualify for at the same income, on top of reducing what is comfortable to carry.
What the fee actually pays for
- Building insurance on the structure and common property — separate from the unit policy you carry yourself.
- Reserve fund contributions, the savings account for major repairs: roof, elevators, parkade membrane, windows.
- Common-area maintenance — landscaping, snow clearing, corridors, management.
- Sometimes utilities, most often heat and water. Two buildings with different fees may simply be drawing the line in different places.
This is why comparing two fees as bare numbers tells you very little. A $520 fee that includes heat and water can be better value than a $390 fee that includes neither.
Why a low condo fee can be the expensive choice
A fee below what the building actually costs to run has to come from somewhere, and the usual source is the reserve fund. An underfunded reserve does not fail quietly — it fails as a special assessment, a lump sum billed to every owner when a major component reaches the end of its life.
That is the risk a first-time buyer is least equipped to see and least able to absorb. It is also entirely checkable before you commit: the reserve fund study sets out what the building expects to spend and when, and the board minutes show what is actually being discussed.
Ask for the reserve fund study, the current budget and the last year of board minutes during your condition period. A healthy reserve is the best evidence that the fee you are quoted today is the fee you will be paying next year.
When buying the condo still wins
Often, and for the same reason it does anywhere: the fee and the mortgage interest are costs, but the principal portion of the payment is not — it becomes equity. Add a market where no provincial land transfer tax applies and the entry cost is unusually low, and a condo purchase in Edmonton can beat renting the equivalent apartment on total monthly cost even after the fee is counted.
The point is not that fees make condos a bad deal. It is that the comparison has to include them, so that whichever way it comes out, you are deciding on real numbers.

Ryan McCann
Ryan is an Edmonton-based REALTOR® with MaxWell Polaris and the person behind Padster. He's helped over 2,200 clients in the Edmonton area buy and sell their home.
Contact Ryan today at 780-964-8445 to talk through your next step.
Last reviewed 22 August 2026. General information for Edmonton-area buyers — not individualized financial, mortgage, legal or tax advice. Mortgage rules, government programs and market figures change; confirm current details with a licensed mortgage professional, an Alberta real-estate lawyer, or the relevant government source before making a decision. Padster is not a brokerage.
Sources
- CMHC — Information for consumers
- CMHC — Calculating GDS / TDS
Your next step
See what your own number actually buys
Every listing is priced by its monthly payment, not just its list price — filter by what you can actually carry.
Open the Edmonton map searchFrequently asked questions
Should I add condo fees to the mortgage payment when comparing to rent?
Yes. Rent is all-in, so the only fair comparison is your rent against the mortgage payment plus the condo fee, plus property tax and unit insurance.
Do condo fees affect how much mortgage I qualify for?
Yes. Lenders include a portion of the condo fee in your gross debt service ratio, which CMHC guidelines cap near 39% of income for insured mortgages. A higher fee lowers the mortgage you qualify for at the same income.
Is a low condo fee a good sign?
Not necessarily. A fee below what the building costs to run usually means the reserve fund is being underfunded, and that shows up later as a special assessment. Judge the fee against what it covers and how healthy the reserve is.
What is a special assessment?
A lump sum billed to every owner when the corporation needs money the reserve fund does not have — typically for a major repair like a roof, elevator or parkade. It is the main financial risk of buying into an underfunded building.
What documents should I ask for before buying a condo in Alberta?
The reserve fund study, the current operating budget, recent board minutes, the bylaws and an estoppel certificate. Review them during your condition period, not after.
Is buying a condo still better than renting once fees are counted?
Frequently, because the principal portion of the mortgage payment builds equity while rent does not, and Alberta's entry costs are low. But it has to be checked per building rather than assumed.